In this guide 8 sections
- 1 Why can’t I get temporary car insurance?
- 2 Am I too young or too old?
- 3 Is my licence the problem?
- 4 Does a past cancellation or refusal count against me?
- 5 Is it the car?
- 6 Will points or a conviction stop me?
- 7 Did I type the registration wrong?
- 8 If the car product will not quote me, what will?
The quote screen says no, or it says nothing at all, and there is no line underneath explaining why. That is deliberate on most quote systems, which are built to avoid telling someone how to change an answer. It is also unhelpful, because the great majority of refusals come down to one of a short list of checks, and most of them have a fix that is not “try another site”.
Why can’t I get temporary car insurance?
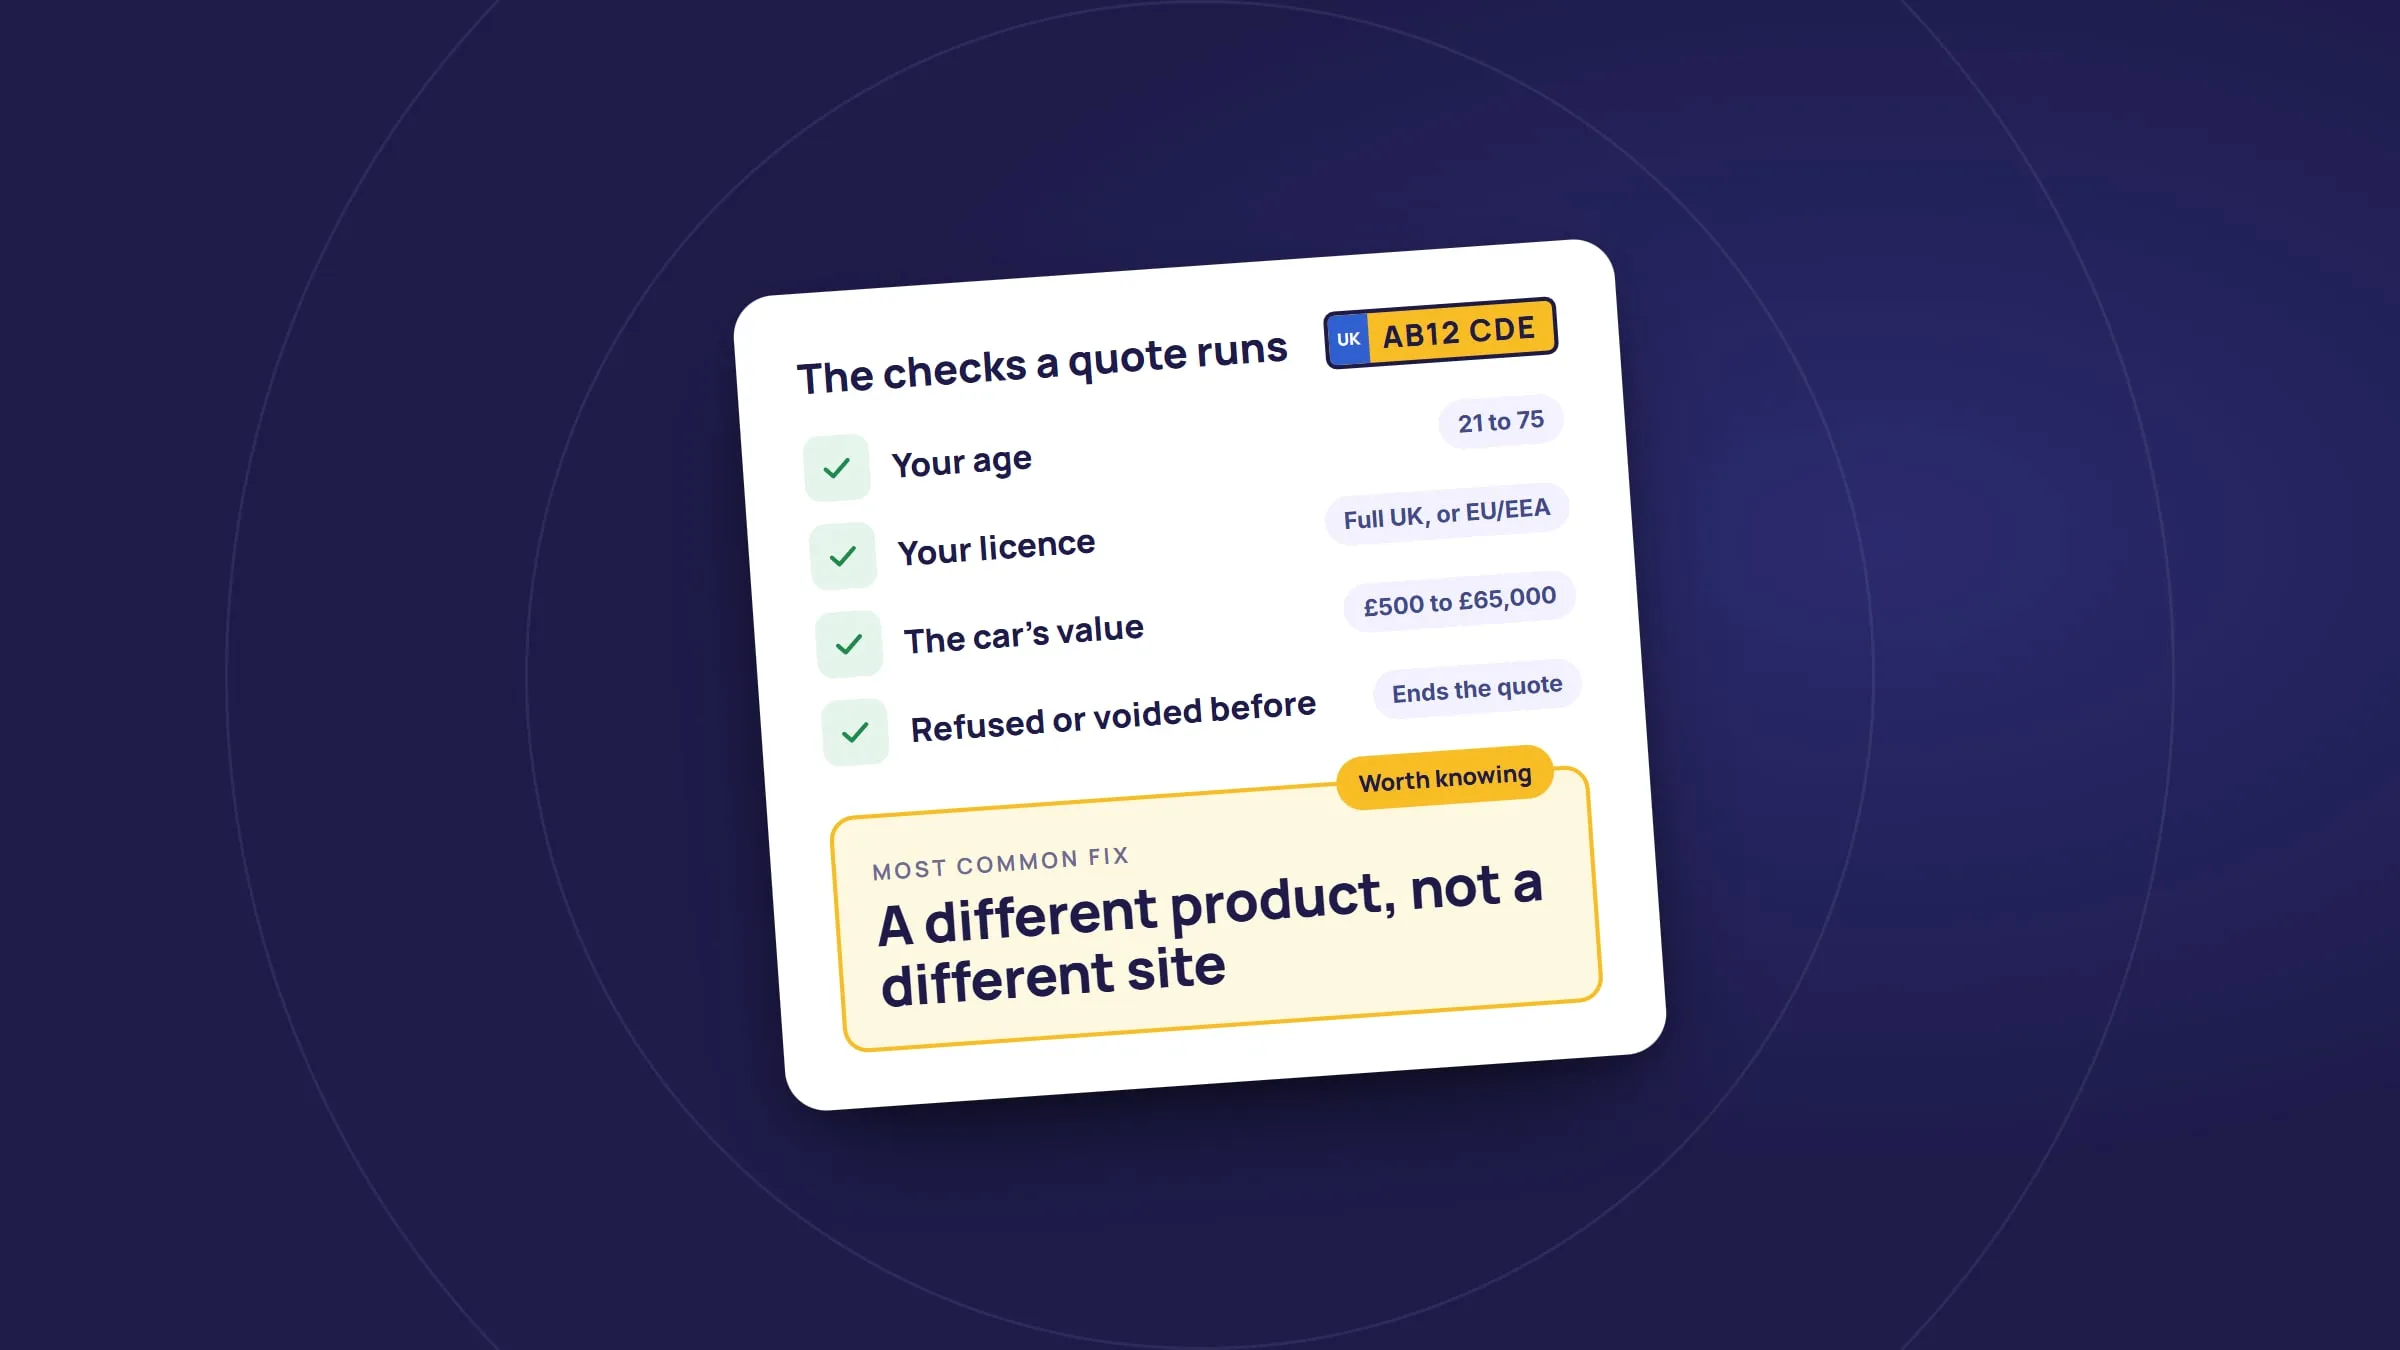
Because one eligibility check failed. For the car product, that is one of nine: your age, your licence, a past refusal or cancellation, the car’s value, its MOT or SORN status, whether it is hired, whether it is modified or imported, whether it is held by the police, or the registration itself.
| Check | The rule on the car product |
|---|---|
| Age | 17 to 75, minimum age by insurer |
| Licence | Full UK, or EU or EEA with 12 months of UK residence with some insurers |
| Your record | Never had insurance refused, cancelled or voided |
| The car’s value | £500 to £65,000 |
| MOT and SORN | Valid MOT; not on a SORN, except to a pre-booked MOT |
| Hire | Not a hire or rental vehicle |
| Modified or imported | Factory options and mobility adaptations only; not imported or left-hand drive |
| Seized | Not held by the police |
| The reg | Must match a DVLA record |
Each has its own section below, with what to do about it.
Am I too young or too old?
The car product covers drivers from 17 to 75, with the minimum age varying by insurer. Provisional licence holders have learner cover from 17; over 75 there is no temporary product on this site.
The age floor is the most common refusal, because the people who most want to borrow a car are the ones under it. A young driver is quoted with the age priced in. On a provisional licence, the product is learner driver insurance, for practising in someone else’s car, from 17. An 18 to 20 year old with a full licence is quoted by some insurers and not others, and the quote shows which.
Over 75, the quote stops. That is the broker’s limit on this product, and this site has no other to offer.
Is my licence the problem?
A full UK licence is quoted, and an EU or EEA licence with 12 months of UK residence is quoted by some insurers. A provisional licence, an international licence or a licence from outside the EEA is not.
Three licence refusals come up:
- Provisional. The car product needs a full licence. Learner cover is the product for a provisional holder.
- International or non-EEA. The product does not accept licences from outside the UK, EU and EEA, even where GOV.UK allows the holder to drive here for a period. Non-UK licence insurance sets out exactly which licences are accepted, and which are not.
- Recently exchanged. A licence exchanged for a UK one in the last few months is a UK licence; what the insurer may look at is how long a licence of any kind has been held. The insurer behind the additional driver product may require 6 months, or 3 months if over 25.
A licence that is suspended or revoked is no licence, and no product covers it.
Does a past cancellation or refusal count against me?
Yes. The standard product asks whether you have ever had insurance refused, cancelled or voided, and a yes ends the quote.
This is the refusal people find hardest, because the cancellation may be years old and may have been for a missed direct debit rather than anything worse. The question does not distinguish. A policy cancelled by the insurer for non-payment, one voided for an answer on the application that turned out to be untrue, and one refused at proposal all count.
The one thing not to do is answer the question wrongly. A policy bought on an untrue declaration is voided at the first claim, which adds another cancellation to the record and leaves the driver uninsured at the moment it matters. Some annual insurers specialise in drivers with a cancellation and will price it; a short policy on the standard temporary product is not available.
Think you pass the checks? Enter the reg and find out.
Get QuotesIs it the car?
The car must be worth between £500 and £65,000, with each insurer setting its own band, have a valid MOT, not be on a SORN, not be a hire car, not be imported or modified, and not be held by the police.
- Value. Under £500 and the insurer’s view is that the car is not worth comprehensive cover; over £65,000 and it is outside the product. Vans go to £65,000 on their own product; motorhomes to £40,000.
- MOT. The car needs a valid MOT, or a pre-booked test that the policy is bought to drive to.
- SORN. A car declared off the road is excluded except for the journey to a pre-booked MOT. If the car has been laid up, tax it first, which ends the SORN, then quote.
- Hire. A rental car has the rental company’s cover; the product excludes hired vehicles. A car lent by a garage or a friend is not hired, and courtesy car insurance covers it.
- Modified or imported. Factory options and mobility adaptations are fine. Aftermarket wheels, a remap, a body kit, a non-standard exhaust, a left-hand-drive car and a car imported from outside the UK are not.
- Seized. A car in a police pound is excluded from the standard product and needs impound release insurance.
Weight is a separate matter. The car product covers vehicles up to 3.5 tonnes; a van goes on the van product.
Will points or a conviction stop me?
Sometimes. Points, convictions and ended bans are declared and priced within each insurer’s limits. A high points total, a refused code, a recent ban, a ban still running or an undeclared conviction is what stops a quote.
Every DVLA conviction code is asked for on the form, and each insurer sets its own limits: from 3 to 9 points, some codes refused outright, and a ban that must have ended two to five years ago. The convicted driver page sets them out. Beyond those limits, two things stop every quote:
- A ban that has not ended. No licence, no cover, on any product.
- A conviction left off the form. The quote may go through and the policy be issued, and it is void from the start. The DVLA record is checked at a claim.
A pending prosecution must be declared, and the insurer decides. The learner product is the stricter one: it asks for no points at all.
Did I type the registration wrong?
Often. A transposed letter looks up a different car, or no car, and the quote fails before any rule is applied.
Check the plate against the V5C, not from memory. O and 0, I and 1, S and 5 are the usual swaps. A car registered in the last few days, a private plate transferred this week, or a car the DVLA has no record of will also return nothing, and the fix is to wait for the record rather than to try again.
If the car product will not quote me, what will?
The site has products for most of the refusals: learner cover from 17, convicted driver cover within each insurer’s limits, impound cover for a seized car, van cover for anything over a car. The two it has nothing for are a running ban and a past cancellation.
| Refused because | Try instead |
|---|---|
| Under 21, provisional licence | Learner driver insurance |
| Under 21, full licence | The car product, with the insurers that quote from 17 |
| Licence from outside the EEA | Nothing here; check non-UK licence insurance for what is accepted |
| Points or a conviction | Convicted driver insurance |
| Car seized by the police | Impound release insurance |
| It is a van | Temporary van insurance |
| It is a motorhome | Temporary motorhome insurance |
| Past cancellation or void | A specialist annual insurer |
| Ban still running | Nothing, until it ends |
A refusal is a fact about one product on one day, not a verdict on the driver. The quote that comes back on the right product is usually just as quick.